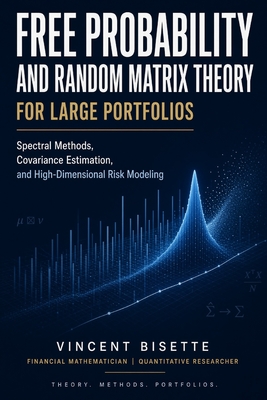
Free Probability and Random Matrix Theory for Large Portfolios: Spectral Methods, Covariance Estimation, and High-Dimensional Risk Modeling
暫譯: 大型投資組合的自由機率與隨機矩陣理論:譜方法、協方差估計與高維風險建模
Schwartz, Alice, Bisette, Vincent
- 出版商: Independently Published
- 出版日期: 2026-08-16
- 售價: $1,540
- 貴賓價: 9.5 折 $1,463
- 語言: 英文
- 頁數: 380
- 裝訂: Quality Paper - also called trade paper
- ISBN: 9798193070979
- ISBN-13: 9798193070979
-
相關分類:
機率統計學 Probability-and-statistics
海外代購書籍(需單獨結帳)
相關主題


商品描述
Modern portfolio construction operates in a high-dimensional regime where the number of assets routinely approaches or exceeds the number of observations. Classical covariance estimators break down in this setting, producing unreliable risk forecasts, distorted principal components, and unstable optimization results.
This book develops the mathematical and computational framework needed to address these failures. It presents free probability and random matrix theory as practical tools for spectral analysis, covariance estimation, and risk modeling of large portfolios. Readers move from the Marchenko-Pastur law and free convolution to concrete procedures for cleaning empirical spectra, recovering population eigenvalues, and constructing robust risk measures under realistic market conditions.
Core topics include:
- Spectral methods for high-dimensional covariance matrices
- Free deconvolution and eigenvalue cleaning techniques
- Bias-corrected estimators for portfolio risk and factor models
- Applications to covariance shrinkage, principal component analysis, and stress testing
- Numerical implementation considerations for realistic asset universes
The material is self-contained yet rigorous, bridging theoretical results with the requirements of quantitative portfolio management. It is written for researchers, quant developers, and advanced practitioners who need reliable tools when classical multivariate statistics no longer apply.
Vincent Bisette provides a focused treatment of free probability and random matrix methods tailored to the specific challenges of large-scale financial risk modeling.